


One of the Most Important AI Stocks Isn’t Nvidia. It’s TSMC
One of the Most Important AI Stocks Isn’t Nvidia. It’s TSMC
Vandita JadejaFri, October 9, 2026 at 4:00 PM UTC
0
Taiwan Semiconductor (Taiwan Semiconductor)Nvidia grabs the AI headlines, but every leading-edge chip it sells has to pass through one company's factories first, and that company trades at a fraction of its biggest customer's valuation.Quick Read -
TSMC earns a BUY rating with a $552 price target, implying 17% upside, as the essential manufacturer behind every leading-edge AI chip.
TSMC trades at 21x forward earnings, which is cheaper than Nvidia at 25x and Broadcom at 19x, despite manufacturing chips for both companies and growing revenue 36%.
August revenue surged 53% year over year, pushing management to raise full-year growth guidance above 40% and lift 2026 capex to $64 billion.
Just released. Our analysts combed the entire stock market and named the ten best stocks to buy right now, and Taiwan Semiconductor Manufacturing didn't make the cut. Enter your email to see the names that beat TSM. The report is free. Enter your email and see if any of your stocks made the cut.
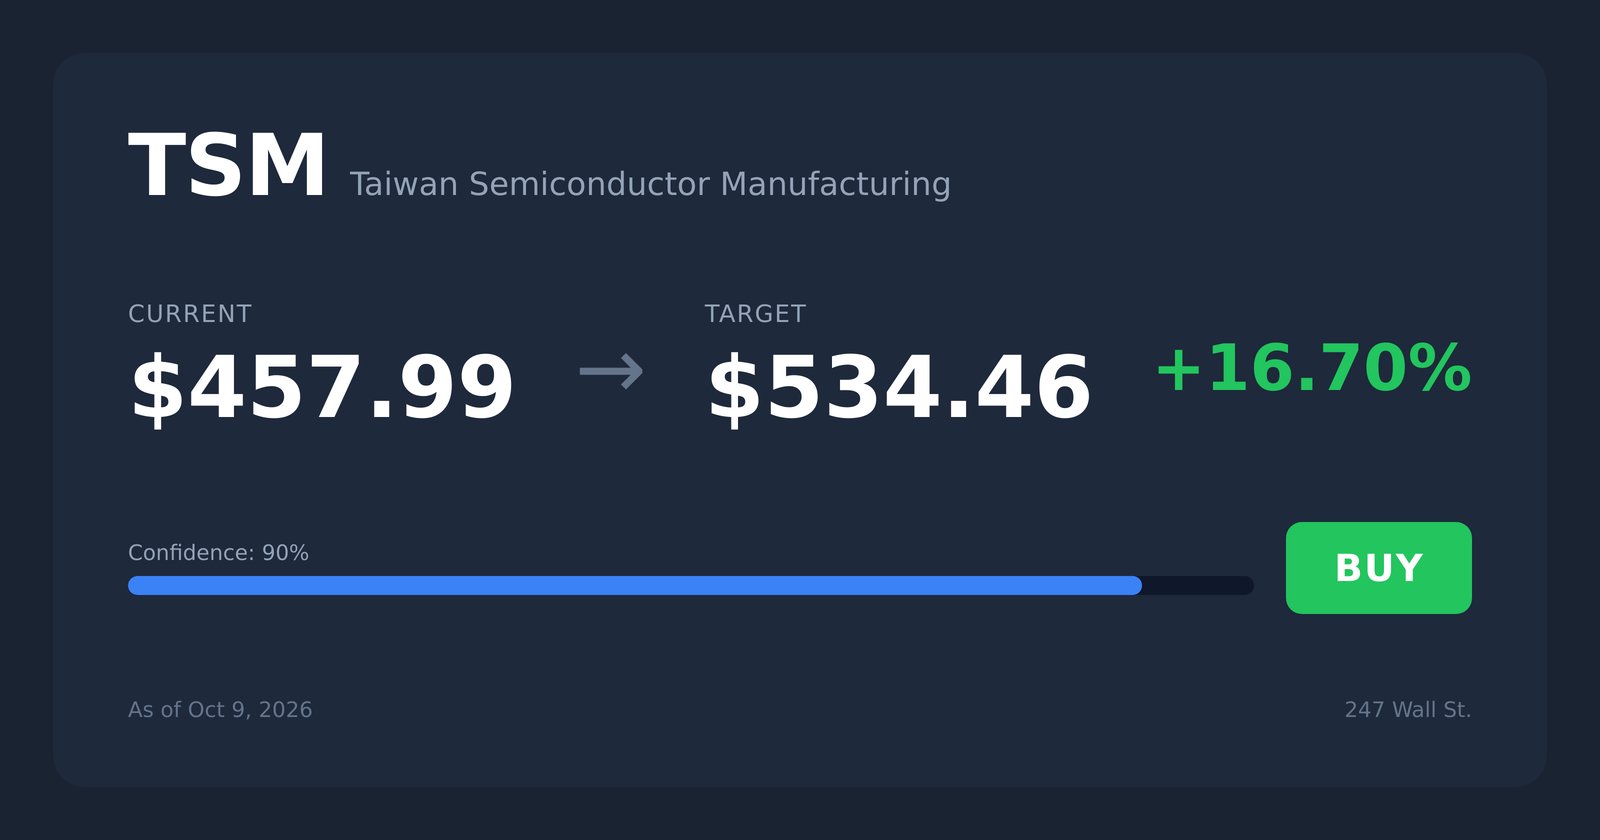
Our 24/7 Wall St. price target for Taiwan Semiconductor Manufacturing (NYSE:TSM) is $552.36. With shares at $472.36, that points to 16.9% upside over the next 12 months.
Metric
Value
Current Price
$472.36
24/7 Wall St. Price Target
$552.36
Upside/Downside
16.9%
Recommendation
Confidence Level
90%
TSMC earns a buy rating with high confidence in this model. NVIDIA (NASDAQ:NVDA) gets most of the AI headlines, but nearly every leading-edge accelerator, including Nvidia's own, goes through TSMC's fabs first. That role as the toll collector on AI silicon is the center of our thesis.
TSM Price Target — 24/7 Wall St.A 2nm Ramp and 53% Revenue Growth Keep TSMC Near 52-Week Highs
Shares rose 3.37% over the past week and 10.42% over the past month, and they are up 56.63% year to date. The stock sits 3.1% below its 52-week high of $487.47 and 78.7% above its low.
Second-quarter EPS of $4.31 beat the $3.887 estimate. Revenue rose 36% to $40.20B, and gross margin reached 67.7%. August revenue then grew 53.3% year over year. Management lifted full-year growth guidance to "slightly above 40%" and raised 2026 capex to $60 billion to $64 billion.
Free Report, Just Released
Why Didn't TSM Make The Top 10 List?
24/7 Wall St has helped investors make money for over two decades, and our top analysts just finished ranking the definitive Top 10 Stocks To Buy Now. Not the ten biggest companies. Not the ten everyone is arguing about. The ten best stocks to buy right now.
And TSM didn't make the cut!
The report is free, and you can see why we think each stock is a top investment today.
Enter Your Email and See the Ten →
Why Bulls See $612 Within Reach
Management sees demand staying strong "all the way to probably 2029, 2030". Advanced packaging capacity is still tight, and A14 volume production is scheduled for 2028.
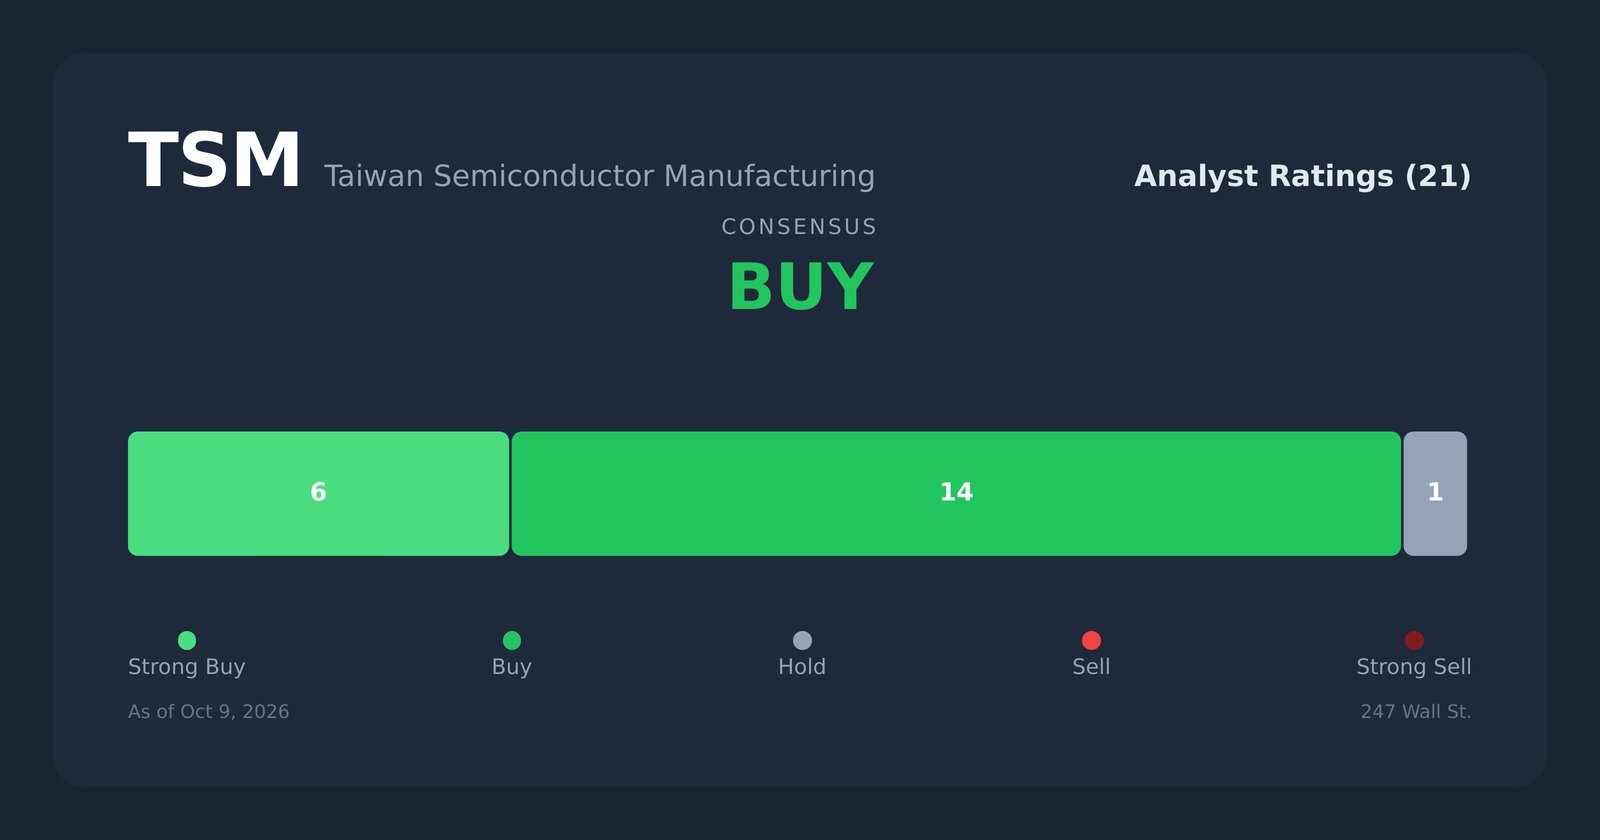
The consensus target of $555.01 is supported by 6 Strong Buy and 14 Buy ratings. If the market pays 30x forward EPS, the stock would reach $612, about 29.5% above today's price.
Advertisement
TSM Analyst Ratings — 24/7 Wall St.Margin Dilution and Taiwan Risk Could Cap Gains
Management expects the 2nm ramp to reduce gross margin by about 3 to 4 percentage points, and third-quarter guidance calls for 65-67%. Cross-strait tensions, currency moves and heavy capex add further risk.
If the multiple contracted to 18x, shares would fall to $367, a 22.3% decline. On the other side, that same guidance still implies strong margins.
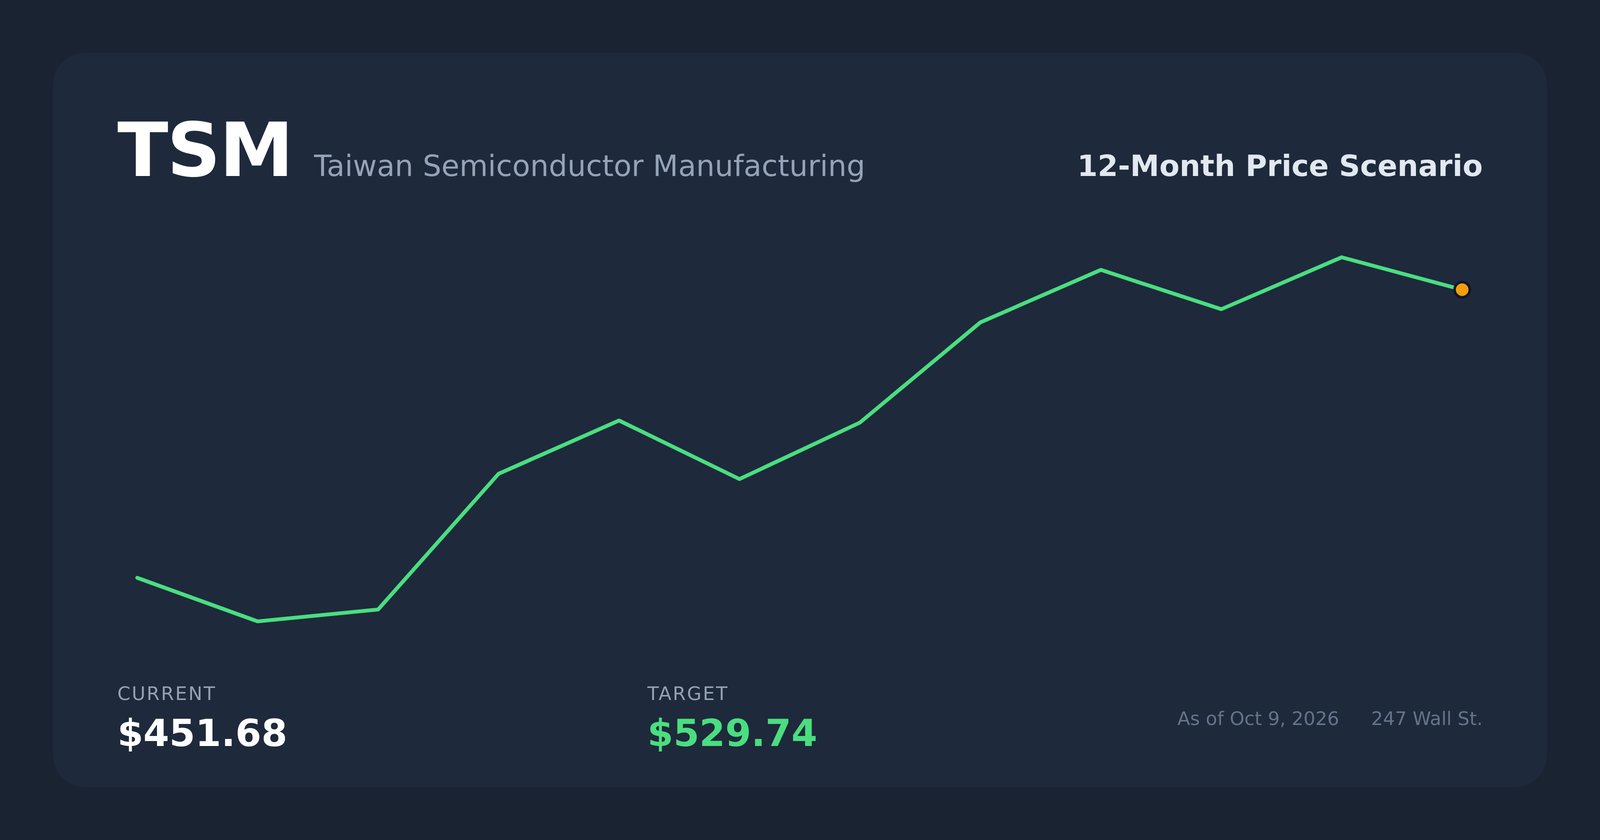
TSM Price Scenario — 24/7 Wall St.TSMC Trades Cheaper Than Its Biggest AI Customers
Nvidia is TSMC's top customer. It trades at 25x forward earnings while revenue grew 105.9%.
Broadcom (NASDAQ:AVGO), a major custom-silicon customer, trades at 19x with AI semiconductor revenue up 221%.
Intel (NASDAQ:INTC), TSMC's main foundry rival, recorded a $2.1 billion quarterly foundry loss, which shows how hard TSMC's lead is to copy.
Company
Forward P/E
Quarterly Revenue Growth YoY
21x
36%
Nvidia
25x
106%
Broadcom
19x
86%
TSMC grows more slowly than its customers but takes a cut from every one of them. Next to these peers, the 24/7 Wall St. price target looks reasonable.
TSMC's Risk-Reward Leans Positive
A 24/7 Wall St. price target of $552.36 comes with a buy rating and 90% confidence. What tips the scale is pricing power on leading-edge nodes that no competitor can yet match.
The setup looks strongest if the 2nm reduction stays within guidance and packaging capacity catches up. It weakens if Taiwan tensions rise or hyperscalers cut AI spending.
Here is where our model projects TSMC could trade if current growth trends and market conditions hold.
Year
24/7 Wall St. Price Target
2026
$492
2027
$580
2028
$684
2029
$787
2030
$881
These projections assume TSMC keeps performing toward its long-term revenue CAGR target of about 25%.
A Taiwan Strait shock or an AI capex slowdown could produce major downside. The flip side is that the biggest winners in AI silicon tend to share a few early characteristics, something we broke down in a free playbook on the next Nvidia.
Got $1,000? Before You Buy TSM, Read This
If you have cash sitting in your account right now, give this two minutes. After more than two decades of helping investors beat the market, our top analysts at 24/7 Wall St. put together a definitive report on the Top 10 Stocks To Buy Today. And TSM wasn't one of them.
They combed the entire market. It's not 10 ideas, not 10 stocks everyone is talking about, it's what their research points to as the 10 best stocks to buy right now, and it's free. Read more here and see which stocks made the list -->>
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
